Why Waiting Too Long to Get a Reverse Mortgage Can Create Problems
Key Takeaways
- A reverse mortgage property still has to meet applicable appraisal and property-condition requirements.
- Roof leaks, water damage, safety concerns, unfinished work, and non-functioning property components can create delays.
- Some HECM property issues may qualify for a repair set-aside, while others may have to be corrected before closing.
- Looking into a reverse mortgage before there is a financial emergency can give a homeowner more time and more options.
A lot of homeowners think a reverse mortgage is something you consider only after the money is running out.
That can be exactly when the process becomes more difficult.
I have talked with homeowners who felt they were doing fine and decided to wait. Then the roof started leaking. A water heater failed. Plumbing developed a problem. Repairs were postponed because money was getting tighter.
Eventually, the homeowner was ready to look at a reverse mortgage, but now the condition of the house had become part of the problem.
That is one reason I would rather have someone explore the option early, even if they ultimately decide they do not need a reverse mortgage yet.
The House Still Has to Qualify
A reverse mortgage is secured by the home, so the property’s condition matters.
For an FHA-insured Home Equity Conversion Mortgage, or HECM, FHA generally requires the property to meet standards intended to make sure it is safe, sound, and secure.
The home does not need to look like a newly remodeled model home. Cosmetic imperfections are not automatically a problem.
But conditions that affect safety, structural soundness, habitability, or the property’s ability to serve as acceptable collateral can require additional attention.
This is where homeowners can run into an unexpected problem.
They may be thinking:
“I need the reverse mortgage so I can afford to fix the house.”
But the condition they need the money to repair may also be something that has to be addressed as part of the reverse mortgage process.
A Roof Problem Can Become a Loan Problem
Roof issues are a good example.
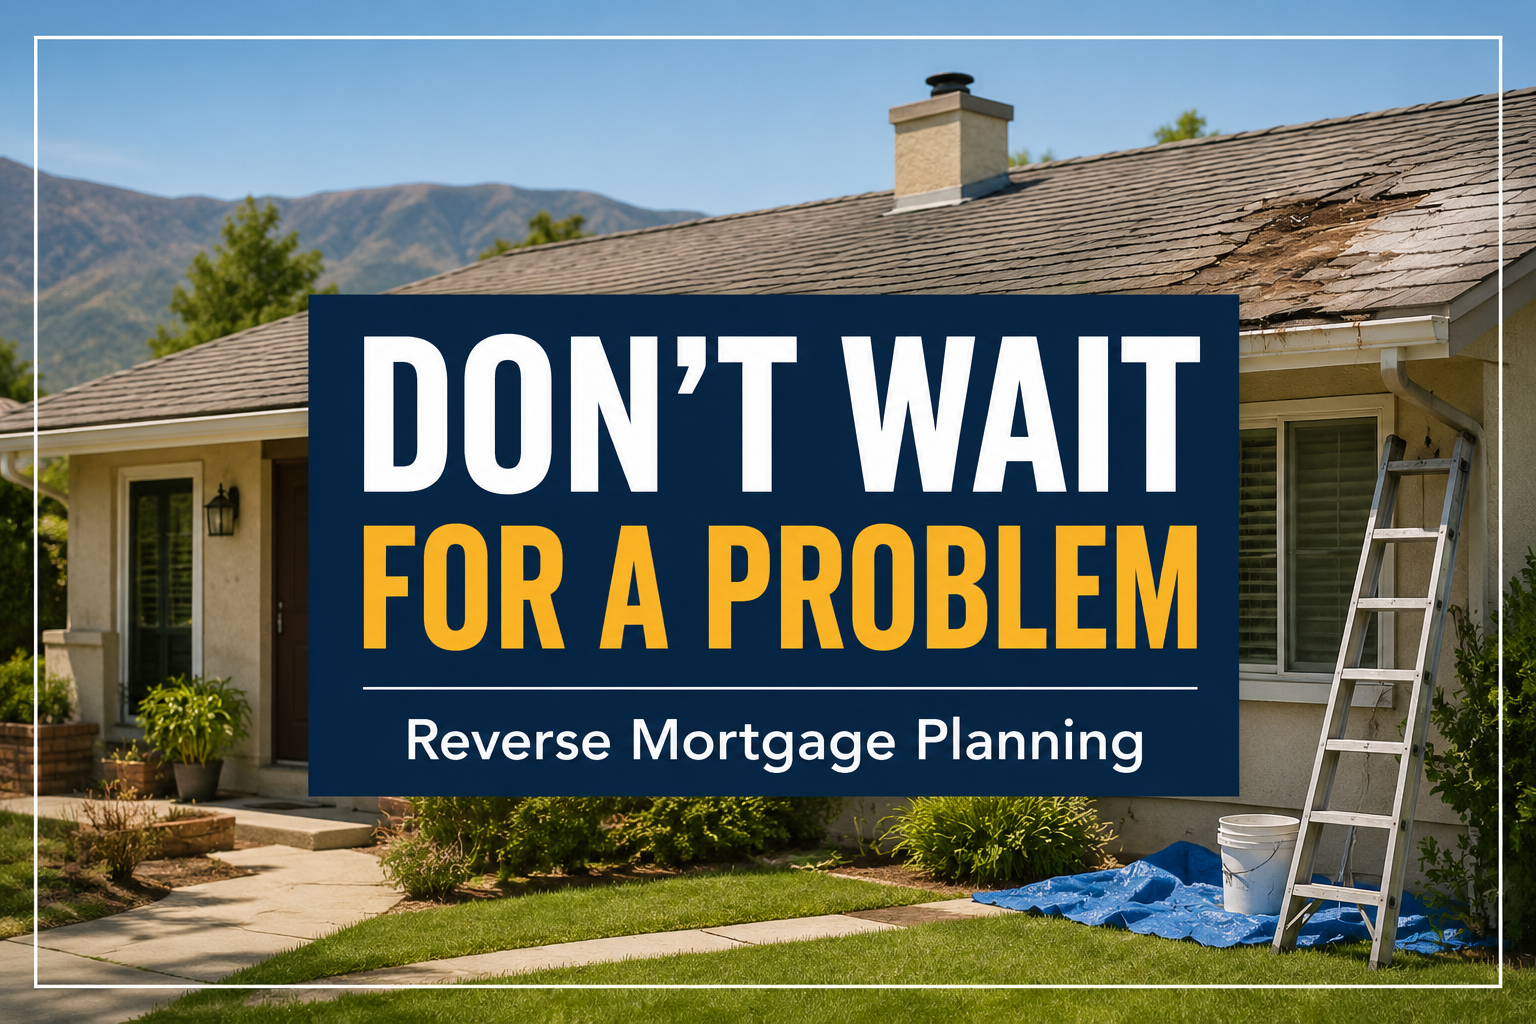
A few old shingles are one thing. An active leak, significant deterioration, damaged roofing, or interior water damage may be another.
Water stains can also raise questions.
Even if a leak was repaired several years ago, visible staining may cause an appraiser or underwriter to want additional information confirming that there is no active problem.
I have seen situations where homeowners needed loan proceeds to deal with deferred maintenance, but the condition of the property complicated their ability to get to closing.
That is a much more stressful position than identifying the problem six months or a year earlier.
Basic Property Systems Matter
The appraiser is not performing the same type of inspection that a licensed home inspector performs. FHA appraisers report readily observable property conditions and evaluate the home under FHA appraisal requirements.
That can include items involving:
- Heating systems
- Plumbing
- Electrical systems
- Water supply
- Roof condition
- Windows and doors
- Safety hazards
- Appliances that remain with the property and contribute to its market value
For example, FHA guidance states that appliances remaining with the property and contributing to the appraiser’s market-value opinion must be operational. That can include a range or oven. :contentReference[oaicite:1]{index=1}
Something as ordinary as a non-functioning appliance can therefore become another item that needs to be addressed.
Small Problems Can Add Up
One small repair usually does not concern homeowners very much.
But several small problems can tell a different story.
For example:
- A plumbing leak under a sink
- Water staining on a ceiling
- Broken glass
- Loose or missing handrails
- Damaged electrical components
- Missing required safety equipment
- Deteriorated exterior surfaces
- Unfinished construction
Individually, some of these may be inexpensive to correct.
The problem is discovering all of them after the appraisal, when the homeowner is already trying to complete a loan.
Thinking About a Reverse Mortgage Before You Need One?
A preliminary conversation can help identify potential property, timing, and loan-structure issues before they become urgent.
Explore Your OptionsSome Repairs May Be Allowed After Closing
One important distinction is that not every property issue automatically means a HECM cannot close.
Under FHA HECM rules, certain defective conditions may be handled through an approved repair set-aside. This allows funds to be reserved for eligible repairs that are completed after closing.
That does not mean every repair qualifies.
The lender still has to review the appraisal and determine whether the property meets FHA requirements and whether the particular repairs are eligible to be completed after closing. If the condition cannot be corrected in an acceptable manner, the property may not qualify. :contentReference[oaicite:2]{index=2}
This distinction is important because homeowners sometimes hear that a reverse mortgage can provide money for repairs and assume that any property condition can simply be fixed afterward.
That is not always the case.
Unfinished Remodeling Can Cause Problems
Another situation I watch for is a homeowner who is already in the middle of a remodeling project.
Maybe the flooring was removed but the new flooring has not been installed. A bathroom was demolished but not completed. A portion of the roof is under construction. Walls are open or electrical work is unfinished.
The property generally needs to be suitable for occupancy and acceptable as collateral.
Starting a major project immediately before an appraisal without understanding how it could affect the loan can create an avoidable delay.
California Homes Can Have Additional Details to Watch
California homeowners may also encounter state and local requirements that become relevant during the appraisal or lending process.
Water-heater installation, smoke alarms, carbon-monoxide alarms, safety devices, and other property items are examples of details worth checking before the appraisal.
The exact requirements can depend on the property, location, loan program, and applicable building or safety standards.
The larger lesson is simple: do not assume that something is too small to matter just because you have lived with it for years.
The Biggest Problem May Be the Timing
The repair itself is often manageable.
The harder part is dealing with it when the homeowner is already under financial pressure.
Now several things may be happening at once:
- The homeowner needs money.
- A repair is urgently needed.
- The appraisal has identified additional work.
- A contractor has to be found.
- There may be another inspection or appraisal visit.
- The loan timeline may be extended.
What could have been a relatively straightforward process can become stressful very quickly.
A Little Preparation Can Make a Big Difference
This is why I like to discuss the condition of the home before the appraisal is ordered.
I am not a home inspector, and a preliminary walk-through cannot guarantee what an appraiser will or will not require.
But obvious issues can often be identified ahead of time.
If I see a ceiling with a large water stain, an unfinished remodeling project, a broken window, or something else that is likely to attract attention, I would rather discuss it before the appraisal than afterward.
That gives the homeowner time to decide what to do without the pressure of an active appraisal condition.
You Do Not Have to Wait Until You Need the Money
A reverse mortgage does not have to begin as an emergency solution.
For some homeowners, it can be part of a longer-term retirement or housing strategy. For others, it may never make sense at all.
But learning how the program works does not obligate you to take out the loan.
Exploring the option while the home is in reasonable condition, finances are still manageable, and there is time to make decisions can provide something that becomes very valuable later:
options.
Bottom Line
Waiting until you are completely out of money is not necessarily the best time to start investigating a reverse mortgage.
When deferred maintenance begins to accumulate, property-condition requirements can make the process more complicated.
A leaking roof, water damage, unfinished remodeling, safety issue, or non-functioning property component may mean repairs, additional documentation, a repair set-aside, or additional review.
The purpose of looking into the loan early is not to rush someone into borrowing money.
It is to understand what is available while there is still time to make choices.
Frequently Asked Questions
Can I get a reverse mortgage if my home needs repairs?
Possibly. The answer depends on the nature and severity of the repairs and the reverse mortgage program being used. With an FHA-insured HECM, certain eligible repairs may sometimes be completed after closing using a repair set-aside. Other conditions may have to be corrected before the loan can close.
What home repairs commonly create reverse mortgage delays?
Potential issues can include active roof leaks, significant water damage, plumbing or electrical problems, broken windows, safety hazards, deteriorated property components, unfinished construction, and other conditions identified during the appraisal or underwriting review.
Why does a roof problem matter for a reverse mortgage?
The roof protects the property from water intrusion and deterioration. If an appraiser observes an active leak, significant roof damage, or evidence suggesting an unresolved problem, additional inspection, documentation, or repairs may be required.
Can reverse mortgage proceeds be used to make home repairs?
Reverse mortgage proceeds can generally be used for many purposes after applicable loan obligations and closing requirements are satisfied. For an FHA HECM, certain required property repairs may also be eligible for an approved repair set-aside. Eligibility and procedures depend on FHA and lender requirements.
Should I wait until I need the money before exploring a reverse mortgage?
There is no requirement to wait for a financial emergency. Learning about the program earlier can give you time to evaluate eligibility, property condition, costs, alternatives, and how a reverse mortgage might fit into your overall plans before a decision becomes urgent.
How can I reduce the chance of appraisal surprises?
Before ordering an appraisal, look for obvious deferred maintenance, water damage, unfinished projects, broken property components, or safety concerns. A preliminary review cannot guarantee what an FHA appraiser will require, but identifying visible issues early can provide additional time to address them.
Important Disclosure: This information is for educational purposes only and is not a commitment to lend or a determination of eligibility. Reverse mortgages are loans and must eventually be repaid. Program requirements, property standards, repair requirements, loan amounts, costs, and eligibility vary by borrower, property, loan program, and lender. For a HECM, borrowers must continue to meet loan obligations, including payment of applicable property taxes and homeowners insurance and maintaining the property. All loans subject to approval. Equal Housing Lender.