Ground-Up Construction Loans
Ground-up construction financing can help experienced builders and real estate investors finance the construction of new residential properties, including spec homes and build-to-rent projects.
Construction loans are structured differently from mortgages on completed properties. Financing may be based on the lot, construction budget, completed value, builder experience, available liquidity, and the planned exit strategy.
Brian Wiesner works with builders and real estate investors to evaluate construction financing options, understand draw requirements and costs, and structure financing around both the construction project and the investor’s longer-term plans.
When Might a Construction Loan Be Used?
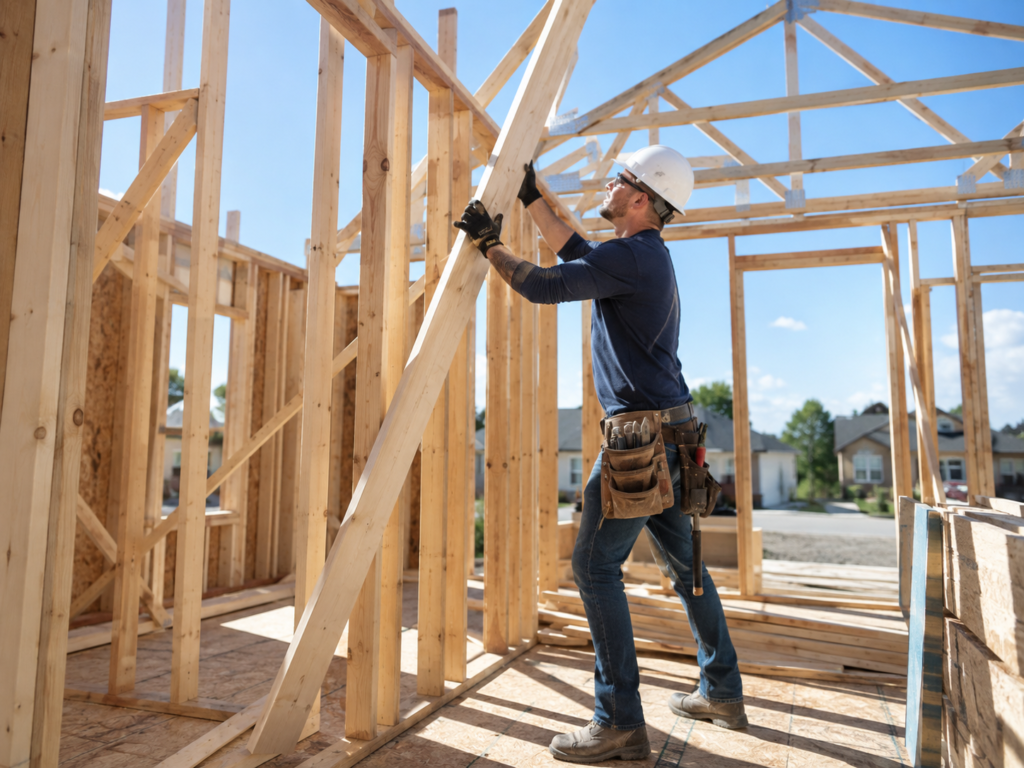
Ground-up construction financing may be appropriate when an investor or builder is developing a new property rather than purchasing an already-completed home. The right financing structure depends on the lot, project budget, builder experience, completed value, timeline, and exit strategy.
Spec Home Construction
Finance the construction of a residential property that will be completed and marketed for sale after construction.
Build-to-Rent Projects
Construct a property that will be retained as a rental and potentially refinanced into permanent investment financing after completion.
Land and Construction Financing
Some programs may finance a portion of the eligible lot cost along with approved construction expenses, allowing the land and construction components to be incorporated into the overall financing strategy.
What Is a Ground-Up Construction Loan?
A ground-up construction loan is short-term financing used to build a new property from the ground up.
Unlike a mortgage on an existing home, the entire construction budget is generally not advanced at closing. Instead, construction funds are typically held by the lender and released through a series of draws as approved stages of construction are completed.
Depending on the program, underwriting may consider the borrower’s construction experience, credit, available assets, project budget, lot value, completed appraised value, contractor qualifications, and exit strategy.
Construction loan terms, loan-to-cost limits, borrower contribution requirements, reserves, draw procedures, fees, and property eligibility vary by program.
How Does Ground-Up Construction Financing Work?
Define the Construction Project
Identify the lot, plans, projected construction costs, expected timeline, completed value, and whether the property will be sold or retained as an investment.
Review the Builder and Project
The lender may evaluate builder experience, credit, liquidity, contractor qualifications, plans, permits, construction budget, and the feasibility of completing the project.
Establish the Construction Loan
The approved loan may provide financing toward the eligible lot cost, approved construction expenses, and other allowable project costs. Construction funds are generally held for future draws rather than advanced all at once.
Complete Construction and Execute the Exit Strategy
Funds are released as construction progresses. After completion, the property may be sold or the construction loan may be refinanced into appropriate permanent financing.
Common Construction Financing Strategies
Ground-Up Construction Loans
Short-term financing designed to take a project from a vacant or improved lot through completion of a new residential property.
Spec Home Financing
Financing for builders and investors constructing a home for resale rather than for a specific owner-occupant who is already under contract.
Build-to-Rent Financing
Construction financing for investors who intend to complete the property, retain it as a rental, and potentially replace the construction loan with longer-term investment financing.
Construction financing may be used for:
Important Construction Loan Considerations
Construction financing involves more than comparing an interest rate and loan amount. The project’s cost, completed value, construction timeline, draw schedule, available liquidity, builder experience, and exit strategy all need to work together.
Guidelines vary significantly by lender and project. Reviewing these issues before purchasing land or beginning construction can help identify financing limitations before substantial capital is committed.
Builder Experience
Many business-purpose construction programs evaluate the borrower’s history of successfully completing construction or substantial renovation projects. Experience requirements vary by program.
Loan-to-Cost and Borrower Equity
Construction lenders may evaluate both the total project cost and the expected completed value. The borrower may be required to contribute equity toward the land, construction costs, or both.
CONSTRUCTION DRAWS
Construction funds are generally released in stages rather than provided as a lump sum. A draw request may require documentation and a third-party inspection confirming that the applicable work has been completed.
Exit Strategy
Construction financing is generally short-term. Before closing, the investor should understand whether the loan will ultimately be repaid through a property sale or replaced with permanent investment financing.
Construction loan programs, loan-to-cost and loan-to-value limits, documentation requirements, builder experience requirements, rates, fees, draw procedures, credit requirements, reserves, property eligibility, and loan terms vary by lender and borrower scenario. Examples are for educational purposes only and do not represent a commitment to lend.
Construction Loan Articles
No posts
Frequently Asked Questions About Construction Loans
Need Help Structuring a Construction Loan?
Construction financing can vary substantially depending on the lot, project budget, builder experience, completed value, property type, construction timeline, and exit strategy.
Reviewing the project before construction begins can help determine which financing structure may fit and identify potential issues before significant time and capital are committed.